Tuesday, October 18, 2016

It's a Journey!!

It's a Journey.  
 Let's make sure that you have all that is needed to begin.

“It’s not far, if you know the way.” What this expression implies is that you could have a long way to go if you don’t know where you’re going or how to get there. Just like reading a map, there are some definite steps that will improve your success in buying a home in today’s market.12137546-250.jpg
  • Know your credit score – the best mortgage rates are available to borrowers with the highest scores. Unless you know what your credit score is at all three major credit bureaus, you don’t really know what rate you’ll have to pay.
  • Clean up your credit – it is estimated that about 90% of credit reports have errors. Some are not serious but others could affect a borrower from getting the loan they want. It is your responsibility to know what is on your different reports and correct them if possible. You’re entitled to a free copy of your credit report each year from Experian, Trans Union and Equifax.
  • Get pre-approved – Taking the time to make a loan application with a qualified lender even before you start looking at homes will provide peace of mind, make sure that you are looking at the “right” homes and may help you negotiate the best price on the home you select.
  • Do your homework – when you find the home that meets your needs and desires, get the home inspected and research the tax assessments, school ratings, crime activity, possible zoning changes and comparable sales in the area.
Call for a recommendation of a trusted mortgage professional and an inspector.

Tuesday, October 11, 2016

Tax Benefits for Surviving Spouse

Surviving Spouse Tax Benefits on the Sale of Your Home.

Special consideration is made by IRS for the sale of a jointly-owned principal residence after the death of a spouse. Surviving spouse may qualify to exclude up to $500,000 of gain instead of the $250,000 exclusion for single people if certain requirements are met.30725703-250.jpg
  • The sale needs to take place no more than two years after the date of death of the spouse.
  • Surviving spouse must not have remarried as of the sale date.
  • The home must have been used as a principal residence for two of the last five years prior to the death. 
  • The home must have been owned for two of the last five years prior to the death.
  • Survivor can count any time when spouse owned the home as time they owned it and any time the home was the spouse’s residence as time when it was their residence.
  • Neither spouse may have excluded gain from the sale of another principal residence during the last two years prior to the death.
If you have been widowed in the last two years and have substantial gain in your principal residence, it would be worth investigating the possibilities. Time is a critical factor in qualification. Contact your tax professional for advice about your specific situation. Contact me to find out what your home is worth in today’s market. See IRS Publication 523 – surviving spouse.

Tuesday, September 27, 2016

Where Were You When You Purchased Your First Home?

A quick tour of the Mortgage Market from the 1970" to Present!  What was your first experience?

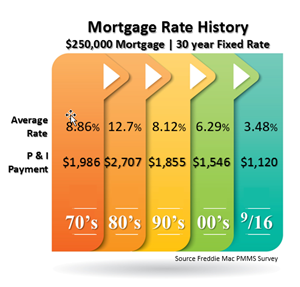
It’s not “if” the rate goes up but “when” the rate goes up; it could make a big difference for some buyers. Freddie Mac predicts that mortgage rates will be at 4.5% a year from now.Mortgage Rate History0916.png
If buyers can afford a home with higher interest rates, it means higher payments. Higher payments might mean they won’t have the money to spend on other things like furniture or improvements to the home or an unrelated purchase like a new car.
When the rate moves 0.50% on a $250,000 mortgage, the payment goes up by $70.66 a month. If it moves 1.00%, the payment goes up by $143.74 per month, each and every month for the entire term of the mortgage which means paying over $50,000 more for the house.
The question facing every borrower in this situation is “How will you feel about having to pay more to live in the same house because you were not ready to commit?”
Then, there’s the borrower who is absolutely maxed out as to what they can qualify for or sometimes, it is a borrower who just refuses to pay a higher payment. When that’s the case, the buyer has to make a larger down payment. In the same example, a 0.50% increase in rate would require $14,873 more in down payment. That could make the purchase impossible or require the buyer to buy a lesser price home that will not have the same amenities.
Mortgage rates have been low for so long that some people think that is what they should be. There are some economists who believe that the economy will not be strong again until mortgage rates are in the 7% range.
To see how this type of scenario might affect you, go to the If the Rate Goes Up calculator.

Friday, September 23, 2016

When To Visit A House Of Interest.

What is the best time to visit a house that you are interested in?  This chart may be of interest to you in making a decision.


Monday, September 19, 2016

How is the Housing Market in your Area?

Here is an insight into the Housing Market in Your Area.  If you are looking to Purchase or Build.

http://eyeonhousing.org/2016/09/sale-and-contract-prices-per-square-foot-in-2015/


SOC_sqftprice15

Monday, September 12, 2016

Getting ready to be inside for the Winter..

With the doors open during the Spring, Summer and Fall, I have noticed a collection of dust around the house, I am sure that I am not alone.

Having a dust-free home isn’t difficult, but it takes a serious commitment and a housekeeping strategy that addresses the dust and its causes. Whether your motive is cleanliness or to eliminate the cause of some allergies and asthma symptoms, it will be worth it.10043513-250.jpg
  • Try to dust your home at least twice a week. Dust the tallest items and work your way down. Dust picture frames, blinds, baseboards and anything that stands out from the wall.
  • Feather dusters can spread more dust than they collect compared to microfiber cloths that attracts dust because they have an electrostatic charge.
  • Filters on heating and air-conditioning systems should be changed often not only to remove dust from the air but to increase the efficiency of the units themselves. Special HEPA filters can improve the overall indoor air quality.
  • Frequently changing the bag or emptying the container in your vacuum is helpful in eliminating dust.
  • Vacuum the floors at least once a week. Vacuum under furniture and periodically, move appliances to clean behind and underneath. Use the proper attachments to vacuum upholstered furniture and under cushions.
  • Eliminate dust magnets like carpet, heavy drapes and upholstered furniture. Consider hard surface flooring like wood or tile instead of carpet.
  • Keep windows closed to keep dust out.
  • Clean your pillows and drapes.
  • Damp mopping and dusting with plain water helps hold the dust and is environmentally friendly.
  • A humidifier can eliminate static electricity which holds dust.
  • Air purifiers circulate are and capture dust and other pollutants.

Wednesday, September 7, 2016

To Invest or Not To Invest.

Rental Property, is this for me?


contributing factors.png
Rental properties have five primary factors that contribute to the return on investment.  Based on market conditions and investor strategies, the individual motivating factor can change from property to property.
There was a time when the benefit of tax savings to offset income from other sources was considered important to some investors.  However, in today's environment, they are more likely valued as incidental benefits.
Some investors expect appreciation to deliver the satisfactory results which can be reasonable over time if a reliable appreciation rate is used.  Savvy investors today are using conservative estimates for long-term holding periods.
Leverage occurs when borrowed funds are used to control a larger asset.  Positive leverage can actually increase the yield on an investment.  Equity build-up happens due to the amortization of the loan which requires that a portion of the monthly payment reduces the principal owed.
The last component that contributes to a property's yield is the cash flow.  When the rents are greater than the expenses of operating the property and servicing the debt, there is a positive cash flow.  A property with a good cash flow doesn't have to go up in value to justify the investment.
The combination of lower prices, low mortgage rates and rising rents are attracting investors to rental properties that include single-family homes in predominantly owner-occupied neighborhoods.
Even if you were to ignore the benefits of tax savings, potential appreciation and leverage, the attractive cash flows make rental property a very smart investment alternative.  Contact me for more information